
Vola: Cash Advance & Credit
- Rating
- 4.7
- Downloads
- 500.00K
- Content Rating
- Everyone
Vola: Cash Advance & Credit - Screenshots
Pros
- Fast access to funds for eligible users
- Simple application process managed entirely in the app
- Clear repayment schedule before accepting an advance
- May help cover unexpected short-term expenses
- Credit-building features can support financial goals
Cons
- Availability and terms may vary by state and user profile
- Fees can make borrowing expensive for short periods
- Repayment is often scheduled around your next paycheck
- Late payments may lead to additional charges or account issues
- Requires sharing sensitive financial and employment information
Vola: Cash Advance & Credit - Description
- App Name
- Vola: Cash Advance & Credit
- Package Name
- com.messapps.vola
- Developer
- Vola inc.
- Category
- Finance
- Last Updated
- Jan 23, 2019
- Version
- 3.4.15
I approached Vola: Cash Advance & Credit as a practical finance app rather than a shortcut to effortless money. Its promise is straightforward: help eligible users access an advance, watch their spending, plan a budget, and work toward building credit without relying on a traditional credit check. In everyday use, that combination makes it more interesting than a simple payday-style tool, but it also means you need to understand how each part fits your financial situation.
My first impression is that Vola makes the most sense when a small timing problem is the issue. If your income is on the way but an important bill arrives first, an advance may help bridge that gap. It is much less convincing as a permanent answer to a monthly shortfall. The app can organize information and provide short-term flexibility, but it cannot make recurring expenses disappear.
How Vola feels as a current finance app
The app comes from Vola inc. and is listed as a free finance app for everyone. It has reached over 500 thousand installs, with a 4.7 average from around 11 thousand ratings and roughly 2 thousand reviews. Those figures suggest that many people find the basic experience useful, although popularity should not be confused with approval for every individual situation.
Vola’s main appeal is the way it brings several money tasks into one place. Instead of opening one app to inspect transactions, another to think about a budget, and a separate service when an unexpected expense appears, you can begin with Vola and see how those decisions relate. That is especially helpful for someone whose income and bills do not line up neatly.
I would describe the interface as more action-oriented than educational. It is not trying to teach a complete personal-finance course. The useful question is usually immediate: what money is available, what spending pattern is emerging, and whether an advance would solve a specific short-term problem? That focus keeps the experience approachable, but users looking for deep investment analysis or detailed long-term planning will probably find it limited.
The free download is important, but I would not treat “free” as meaning that every financial action has no cost or condition. Cash-advance services can involve eligibility rules, timing considerations, or terms that matter more than the installation price. Before accepting anything, I would read the in-app explanation carefully and check the final amount, delivery expectations, and repayment implications.
The cash-advance feature needs disciplined use
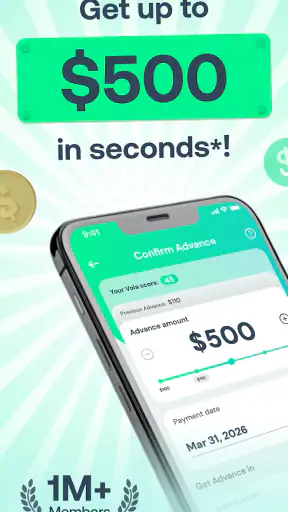
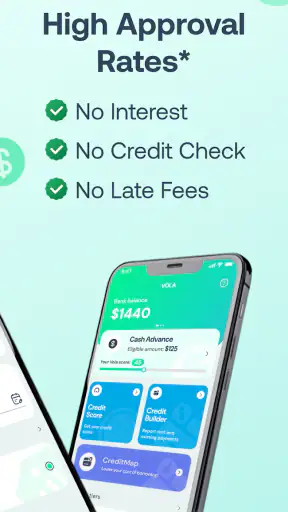
The most obvious reason to install Vola is the possibility of getting an advance without a conventional credit check. That can be valuable for people with limited credit history or for those who do not want a hard inquiry to shape a short-term borrowing decision. It also makes the app relevant to users who are financially responsible in general but have a temporary mismatch between payday and a necessary expense.
My advice is to decide what the advance is for before requesting it. A utility bill, essential transport, or a basic grocery run is easier to evaluate than an impulse purchase. I would also write down the next income date and the expenses already committed to it. If the next deposit is already spoken for, moving money forward may simply create a larger problem later.
A useful workflow is to check the spending view first, identify the exact gap, and then consider the advance only if the amount is genuinely manageable. This reverses the tempting habit of seeing available cash and then finding a reason to use it. In my experience, that small change in order is one of the best ways to keep a convenience feature from becoming a cycle.
There is another trade-off: no credit check can make access feel easier, but it does not remove the responsibility to repay. The absence of a traditional check should never be read as evidence that borrowing is risk-free. Vola may be a sensible bridge for a defined emergency; it is not the right tool for covering a budget that is structurally short every month.
Budgeting and spending tracking are more valuable than they look
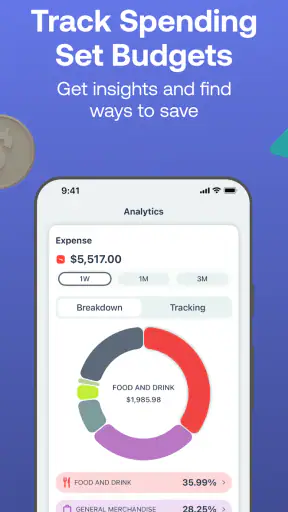
The budgeting side is where the app can become useful even when you never take an advance. Seeing spending in one place can reveal patterns that are easy to miss when you rely on memory. Small purchases, irregular subscriptions, and frequent convenience spending can look harmless individually but become significant when viewed together.
I would use the tracking feature as a weekly check-in rather than waiting for a crisis. A short review can answer three practical questions: which expenses were expected, which were avoidable, and what must be protected before the next income arrives? That approach turns the app from an emergency button into a basic control panel for everyday decisions.
One non-obvious benefit is the connection between the spending picture and the borrowing decision. If the app shows that the problem is a one-time timing gap, an advance may be reasonable. If it shows several categories running over budget repeatedly, the better answer is to adjust those categories, delay a nonessential purchase, or seek a longer-term solution. The same screen can therefore tell you when not to borrow.
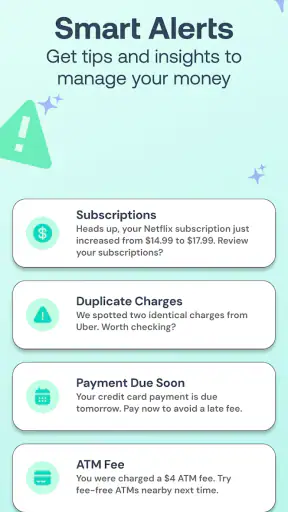
Still, tracking is only useful when the information is complete and understood. I would not assume that an automatically organized transaction view replaces checking statements or confirming unusual activity. Use it as a convenient overview, then verify anything that affects a borrowing decision or a bill payment.
Credit-building changes the way you should judge the app
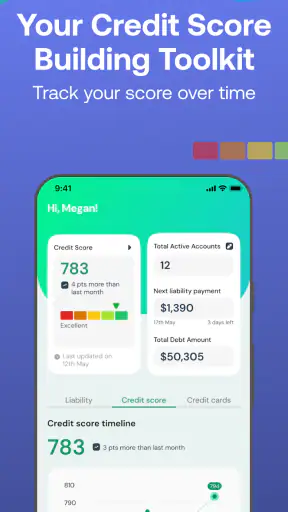
Vola also presents itself as a way to build credit, which gives the app a longer-term angle beyond immediate cash access. That could appeal to someone trying to establish a stronger financial profile, but credit-building claims deserve careful attention. The important details are how activity is reported, what actions qualify, and whether the process matches your goals.
I would not install the app solely because the phrase “build credit” sounds attractive. First, look at the explanation shown inside the service and make sure you understand what participation involves. Credit improvement is usually gradual, and one product cannot substitute for paying regular obligations on time, keeping borrowing controlled, and checking your credit information for errors.
The practical advantage is that Vola places short-term cash management and credit awareness next to each other. That can encourage better habits if you use the advance sparingly and monitor your budget. The danger is treating credit-building as permission to borrow more often. I see the feature as a reason to be more deliberate, not as a reward that makes repeated advances harmless.
What changed, and what existing users should notice
The current version is 3.4.15, while the app has been available since January 23, 2019. That history matters because Vola is not a brand-new experiment; it has had time to develop around the combined needs of advances, budgeting, spending visibility, and credit. Even so, version numbers alone do not tell me that every part of the experience has changed equally.
For an existing user, the sensible approach is to review the current screens and terms rather than relying on an old routine. A familiar button may lead to a revised explanation, an eligibility step may be presented differently, or the spending view may organize information in a way that changes how quickly you can make a decision. I would pay particular attention whenever requesting an advance, because that is where current conditions matter most.
The app’s evolution is most meaningful when it reduces friction without hiding important information. A smoother journey is welcome, but financial apps should make amounts, timing, and obligations easy to understand before confirmation. If a new version makes the process faster, I still want the key details to remain visible and readable.
People upgrading from an older installation should also take a moment to check their budget categories and spending assumptions. A change in presentation can make an old habit less reliable. Rather than assuming that previous settings or interpretations still apply perfectly, I would revisit the dashboard, inspect recent activity, and confirm that the app reflects the way I currently manage money.
For someone new to Vola, the mature version is both a strength and a reason to begin slowly. There is enough history and adoption to make the app feel established, but the right first step is still observation. Install it, understand the tracking view, and learn the advance process before treating it as part of your emergency plan.
A realistic month with Vola
Imagine that your paycheck is scheduled for later in the week, but a necessary car repair cannot wait. I would open Vola and first review the money already committed to rent, food, transport, and other unavoidable expenses. Then I would compare the repair cost with the amount that could realistically be repaid from the next income without leaving another gap.
If the numbers work, the advance may provide useful breathing room. I would save the repair receipt, avoid adding optional purchases, and use the spending view during the following days to make sure the temporary help does not become extra spending power. Once paid, I would reassess whether the same type of problem is likely to recur and adjust my emergency savings goal.
If the numbers do not work, I would skip the advance. That answer may feel disappointing, but Vola is still useful in that scenario because its budget and tracking functions can clarify the shortfall. Perhaps the repair requires a payment arrangement, a different provider, or a broader change to monthly expenses. An app should support a decision, not pressure you into one.
Where the experience still has gaps
Vola is not a replacement for a full bank account, a detailed spreadsheet, or a professional financial adviser. Its strength is quick, practical oversight, not unlimited customization. Users with complicated household finances, multiple businesses, investments, or extensive debt may need tools designed for deeper planning.
I also would not choose it if I want a purely long-term budgeting system with no borrowing component. Some people prefer to keep spending analysis and credit products completely separate, and that separation can make their decisions feel clearer. In that case, a dedicated budgeting app or a bank’s built-in tools may be a better fit.
The app may also be the wrong choice for anyone who tends to spend available money simply because it appears accessible. The convenience of an advance can reduce the psychological barrier that normally encourages caution. If you already struggle with repeated short-term borrowing, I would prioritize debt counseling, a spending freeze, or a sustainable income-and-expense plan instead.
Privacy and account access should be considered in practical terms too. Before connecting financial information, I would read the permissions and explanations presented during setup, use a secure device, and avoid treating the dashboard as an unquestionable record. The more important the decision, the more worthwhile it is to verify the underlying account activity independently.
Another limitation is that a high user rating cannot predict your eligibility or experience. The app’s overall reception is encouraging, but financial products depend on personal circumstances. I would judge Vola by whether its current terms, available tools, and repayment structure fit my needs, not by the average rating alone.
Who should use it, and who should look elsewhere?
I think Vola is best suited to someone who wants a simple way to monitor spending and occasionally manage a clearly defined cash-flow gap. It may be particularly useful for people who are new to credit, want to become more conscious of their spending, or need an alternative to a traditional credit-check process for a short-term situation.
I would recommend caution for anyone with unpredictable income and no reserve at all. Unpredictability does not automatically make the app unsuitable, but it makes repayment planning more difficult. In that case, the budgeting view may still help, while the advance feature deserves a much higher threshold for use.
I would choose a conventional bank overdraft or a carefully compared personal loan when the need is larger, longer, or easier to plan in advance. Those alternatives can offer structures that are more appropriate for a substantial expense, though they also require their own careful comparison. For simple expense visibility, a dedicated budgeting app may provide a cleaner experience without putting borrowing in the foreground.
For credit-building, I would compare Vola’s explanation with established credit products and free credit-monitoring resources before committing. The best option depends on reporting practices, costs, repayment behavior, and how much control you want over the process. Vola is appealing because it combines several jobs, but a specialist tool may be stronger at one job.
What I would watch before making Vola part of my routine
I would keep an eye on how clearly the app explains eligibility, repayment timing, and any charges connected with an advance. These details matter more than a polished interface. I would also watch whether the spending view helps me change behavior or merely gives me an interesting summary after money has already gone.
For credit-building, I would look for transparent explanations of what actions count and how progress should be interpreted. I would avoid assuming that using the app frequently is the same as improving credit. The healthiest sign would be that the service encourages controlled borrowing, regular review, and better planning rather than repeated dependence.
Existing users should watch their own patterns as closely as app updates. If advances become part of every pay cycle, that is a warning that the product is treating a recurring budget problem rather than solving it. If tracking helps you anticipate bills and reduce surprises, then the app is serving its most useful purpose.
My overall view is positive but measured. Vola offers a convenient mix of cash-flow support, spending awareness, budgeting, and credit-focused tools, and its free access makes it easy to explore. I especially like the idea of checking the budget before requesting money, because that turns the app into a decision aid instead of a reflex.
At the same time, I would not recommend using it casually. The absence of a traditional credit check does not remove repayment pressure, and the credit-building angle should be understood rather than assumed. If you need a modest bridge and are confident about the next steps, Vola can be a practical companion. If your expenses regularly exceed your income, a longer-term solution is more important than another advance.
In short, I see Vola as most valuable when it helps you pause, inspect the numbers, and make a controlled choice. Use the tracking and budget features first, treat borrowing as a specific tool for a specific gap, and compare alternatives whenever the need becomes larger or lasts longer. That balance is what makes the app worth considering—and what keeps it from becoming a substitute for a real financial plan.
FAQ
What is Vola: Cash Advance & Credit, and how does it work?
Vola is a financial app designed to help eligible users access cash advances and monitor aspects of their personal finances. After creating an account, you may be asked to connect a bank account and provide information used to determine eligibility. If approved, the available advance, fees, repayment date, and other terms should be reviewed carefully before accepting the offer.
Who can use Vola, and what eligibility requirements should I expect?
Availability depends on factors such as your location, age, identity verification, income activity, linked bank account, and account history. Meeting the basic requirements does not guarantee approval or a specific advance amount. During testing, financial apps of this type may also require a compatible U.S. bank account and recurring deposits, so check Vola’s current requirements in the app or official store listing.
How much does Vola cost, and are there additional fees?
The total cost can depend on the membership plan, cash-advance terms, optional services, and any applicable transaction or expedited-funding charges. Before confirming an advance, carefully inspect the disclosure screen for the amount received, repayment amount, due date, recurring subscription cost, and cancellation rules. Avoid assuming that a free download means every feature is free.
How and when do I repay a Vola cash advance?
Repayment is generally scheduled for a future date and may be collected automatically from the bank account connected to your Vola profile. Make sure sufficient funds are available when repayment is due, because a failed payment could lead to account restrictions, bank charges, or other consequences. Review the repayment schedule and contact support promptly if your circumstances change.
Is Vola safe to use, and what personal information does it access?
Using Vola may involve sharing sensitive information, including identity details, financial data, bank-account credentials through a connection service, transaction history, and contact information. Read the privacy policy and permissions before linking an account, use a strong unique password, and download only from an official app store. A cash advance should be treated as short-term borrowing, not a replacement for regular income.


